 Self-employed bank statement funnel
A self-employed funnel for borrowers tax returns undersell
Business owners write off what they can — and then a lender reads their tax return as low income. Bank statement programs exist for this. This funnel finds those borrowers and explains it honestly.
Included in every plan · or add to any plan for $59/mo
Question 1 of 4
How are you self-employed?
Question 2 of 4
How long have you been self-employed?
Question 3 of 4
Do you have 12–24 months of bank statements?
What it is
What is a self-employed bank statement funnel?
A bank statement loan funnel is a landing page and quiz for self-employed borrowers that asks about business type, how long they have been self-employed and how many months of statements they have, explains how bank statement programs estimate income, and books a call with a loan officer who offers non-QM loans.
Who it's for
Self-employed borrowers, freelancers, gig workers and 1099 contractors whose tax returns show lower income than their deposits, after business deductions.
What makes them search
- Turned down elsewhere
- Recently went self-employed
- Big write-off year
- Buying a bigger home as the business grows
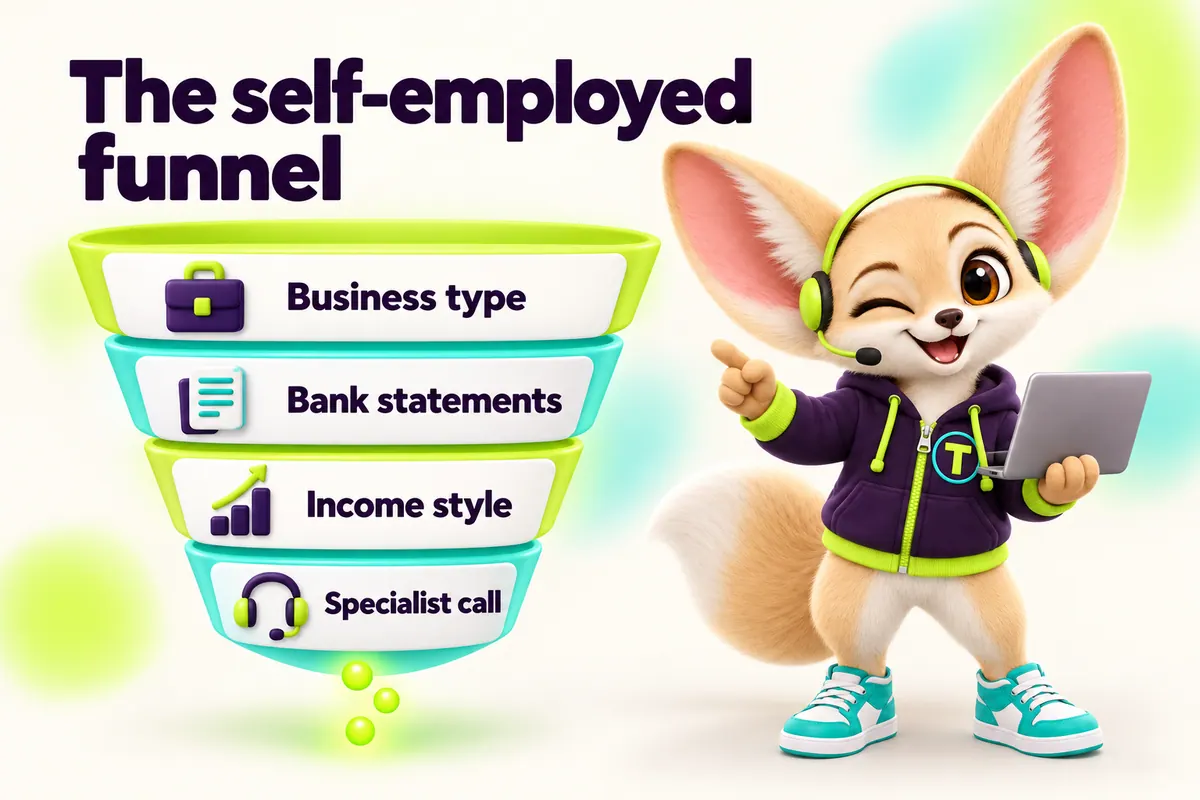
The funnel map
How the Self-employed bank statement funnel moves a borrower
- 01
Ad or link
Ad angle 1 of 2
Self-employed? Your tax return isn't the whole story
- 02
Landing page
One screen, one promise
A bank statement loan funnel is a landing page and quiz for self-employed borrowers that asks about business type, how long they have been self-employed and how many months of statements they have, explains how bank statement programs estimate income, and books a call with a loan officer who offers non-QM loans..
- 03
4-question quiz
Tap-only answers
How are you self-employed? · How long have you been self-employed? · Do you have 12–24 months of bank statements? · What are you planning?
- 04
Result page
Next step, no promises
The result page explains how bank statement programs average deposits over 12 or 24 months and apply an expense factor, lists documents, and books a call. It is clear that rates and terms often differ from conventional loans.
- 05
Handoff & follow-up
4 touches written for you
Business type and statement months go to the CRM so the LO knows which program to discuss.
The questions, word for word
Four taps. No paperwork yet.
This is the quiz we write for you (your edits welcome). Every answer is a button, so it works one-handed on a phone.
Question 1
How are you self-employed?
- Own a business
- Freelance / 1099
- Gig or rideshare
- Partner in a firm
Question 2
How long have you been self-employed?
- Under 1 year
- 1–2 years
- 2+ years
Question 3
Do you have 12–24 months of bank statements?
- Yes, business account
- Yes, personal account
- Some months
- Not sure
Question 4
What are you planning?
- Buy a home
- Refinance
- Buy an investment
Result page
What the borrower sees next
The result page explains how bank statement programs average deposits over 12 or 24 months and apply an expense factor, lists documents, and books a call. It is clear that rates and terms often differ from conventional loans.
Follow-up, written for you
What happens after they tap "done"
The follow-up below runs from the CRM included with your site. Texts only go to borrowers who ticked the SMS consent box. Messages are sample copy — we tailor them to your voice.
- 0–30 secondsSMS
Hi {first}, {LO} here. I work with self-employed buyers often — want to see what your statements could support? {calendar} Reply STOP to opt out.
- 10 minutesEmail
"How lenders read bank statements" — plain explanation and a documents list.
- Day 2Task
LO call task with program notes.
- Day 10Email
"Getting your file ready" — tips on separating business and personal accounts.
Ads & compliance
Ad angles that work — and stay compliant
Sample ad angle
"Self-employed? Your tax return isn't the whole story"
Empathy angle; no "no income verification" claims.
Sample ad angle
"Told no because of write-offs? See other ways lenders review income"
Educational; lists program types, not approvals.
Compliance built in
- Ability-to-repay rules still apply to non-QM loans; copy never says "no income verification".
- Rates and terms often differ from conventional loans — stated plainly.
- No "approved regardless of credit" language.
- NMLS ID and Equal Housing Opportunity on all pages.
We explain public rules; we don't give legal advice. Your compliance team approves every funnel before launch. Mortgage ad compliance, explained.
What we watch
Numbers that tell us it's working
- 1Share with 2+ years self-employed
- 2Booked calls
- 3Applications
- 4Program fit rate on calls
On Funnel Stack and Full Library we test one or two changes a month (a headline, a question order) and report what moved.
Included with this funnel
- Landing page, 4-question quiz and result page, written and built
- Application handoff, pre-filled from the quiz
- 4-touch follow-up in the CRM (SMS with consent, email, tasks)
- 2 ad angles written to avoid unbalanced trigger terms
- Schema, FAQs and your NMLS / Equal Housing block on every page
Not included
- Ad spend (paid to Meta or Google from your account)
- Legal or compliance approval (your compliance team)
- Loan decisions — those stay with you
FAQ
Self-employed bank statement funnel questions
Specific to the self-employed bank statement funnel. General questions live on the FAQ page.
Can't find it? Search every answer or ask the funnel desk.
What is a bank statement loan?
It is a type of non-QM mortgage where the lender estimates income from 12 or 24 months of bank deposits, usually applying an expense factor, instead of relying only on tax returns. It suits self-employed borrowers whose deductions make taxable income look low.
Can the funnel say "no income verification"?
No. Lenders must still make a reasonable, good-faith determination of ability to repay under the CFPB's rule. Bank statement loans verify income differently; they do not skip it. Honest wording protects you and filters for better-fit borrowers.
Who should not be sent to this funnel?
W-2 employees and self-employed borrowers whose tax returns already support the loan. Conventional options are often cheaper for them, and the result page says so and links the pre-approval funnel.
How long must someone be self-employed?
Program rules vary, but many look for around two years of self-employment history. The quiz asks so the LO can set expectations early. The funnel does not publish a fixed rule because it varies by lender.
Do we need non-QM lenders to run this?
Yes. Only build this funnel if your company offers bank statement programs. If it does not, we leave it out of your library.
Can the borrower upload statements through the funnel?
After booking, an optional secure upload request can be sent from the CRM. We avoid asking for sensitive documents on a public landing page before a conversation.
Does the copy work for gig workers?
Yes. Gig and rideshare are quiz options and the explanation covers 1099 income. The LO decides on the call which program fits.
What ad angle works best for self-employed borrowers?
We lead with empathy rather than hype: "Your tax return isn't the whole story" rather than "No docs!". It explains the real benefit, keeps the ad compliant, and attracts borrowers who fit the program. On Funnel Stack and Full Library we A/B test headline angles each month so your own data decides.
No question matches that.
Try fewer words, pick "All", or send us the question — we answer within one business day.
Next stage: booked
Launch the self-employed bank statement funnel in about two weeks
Book a call and we'll review your programs, traffic sources and compliance requirements, then send a written plan for this funnel.
Free 25-minute call · month-to-month plans · no ad spend required to start