 Reverse mortgage (HECM-aware) funnel
A reverse mortgage funnel that families can trust
Reverse mortgages are the most regulated, most misunderstood product an LO can market. This funnel is calm, factual and family-friendly, and it explains the counseling step up front.
Included in every plan · or add to any plan for $59/mo
Question 1 of 4
Who is researching?
Question 2 of 4
Is the youngest homeowner 62 or older?
Question 3 of 4
Is there a mortgage on the home now?
What it is
What is a reverse mortgage (hecm-aware) funnel?
A reverse mortgage funnel is a landing page and quiz for homeowners aged 62 or older and their families that checks age and home basics, explains how a Home Equity Conversion Mortgage (HECM) works including ongoing obligations and the required HUD-approved counseling, and books a no-pressure call with a loan officer.
Who it's for
Homeowners aged 62 and older with significant equity, and the adult children who often research on their behalf.
What makes them search
- Retirement income gap
- Rising property taxes
- Desire to age in place
- Paying off an existing mortgage
The funnel map
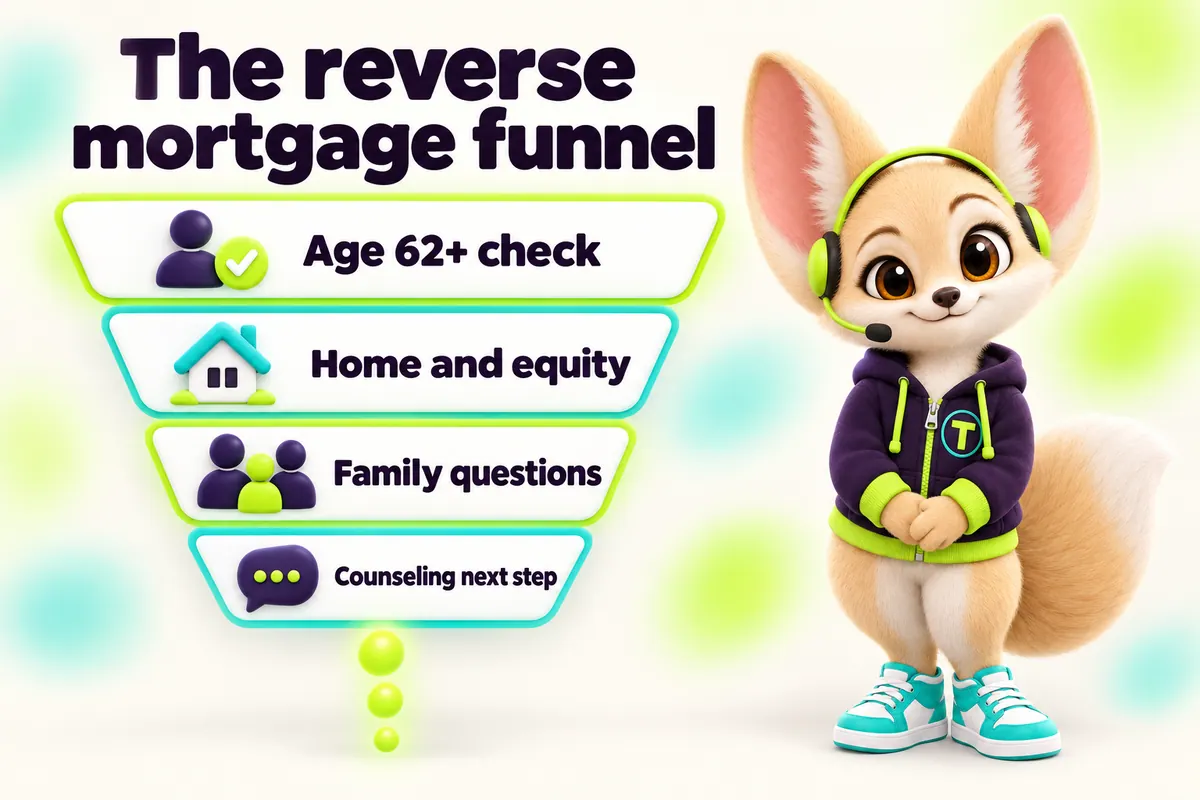
How the Reverse mortgage (HECM-aware) funnel moves a borrower
- 01
Ad or link
Ad angle 1 of 2
Is a reverse mortgage right for your parents? Questions to ask
- 02
Landing page
One screen, one promise
A reverse mortgage funnel is a landing page and quiz for homeowners aged 62 or older and their families that checks age and home basics, explains how a Home Equity Conversion Mortgage (HECM) works including ongoing obligations and the required HUD-approved counseling, and books a no-pressure call with a loan officer..
- 03
4-question quiz
Tap-only answers
Who is researching? · Is the youngest homeowner 62 or older? · Is there a mortgage on the home now? · What matters most?
- 04
Result page
Next step, no promises
The result page explains the basics: the borrower keeps title, must live in the home, and must keep paying property taxes, insurance and upkeep; the loan becomes due when the last borrower leaves; HUD-approved counseling is required before applying. It invites a call that family members can join.
- 05
Handoff & follow-up
4 touches written for you
Researcher type and priority go to the CRM so the LO knows whether family will be on the call.
The questions, word for word
Four taps. No paperwork yet.
This is the quiz we write for you (your edits welcome). Every answer is a button, so it works one-handed on a phone.
Question 1
Who is researching?
- I'm the homeowner
- For my parent(s)
- A financial advisor
Question 2
Is the youngest homeowner 62 or older?
- Yes
- Within a year or two
- No
Question 3
Is there a mortgage on the home now?
- Paid off
- Small balance
- Larger balance
Question 4
What matters most?
- Monthly cash flow
- Pay off the mortgage
- A safety line of credit
- Staying in the home
Result page
What the borrower sees next
The result page explains the basics: the borrower keeps title, must live in the home, and must keep paying property taxes, insurance and upkeep; the loan becomes due when the last borrower leaves; HUD-approved counseling is required before applying. It invites a call that family members can join.
Follow-up, written for you
What happens after they tap "done"
The follow-up below runs from the CRM included with your site. Texts only go to borrowers who ticked the SMS consent box. Messages are sample copy — we tailor them to your voice.
- 5 minutesEmail
"Reverse mortgages: the plain-English guide" — obligations, counseling, questions to ask any lender.
- Same dayCall
LO call — no automated texts unless the borrower opted in.
- Day 3Email
"How HUD-approved counseling works" — with a link to HUD's counselor search.
- Day 14Email
"Questions families ask" — with the LO's booking link.
Ads & compliance
Ad angles that work — and stay compliant
Sample ad angle
"Is a reverse mortgage right for your parents? Questions to ask"
Family-research angle; educational.
Sample ad angle
"How a HECM works — taxes, insurance and counseling explained"
Lead with obligations to build trust.
Compliance built in
- No "you can never lose your home", "tax-free money forever" or "government benefit" claims — the CFPB has warned about misleading reverse mortgage ads.
- Obligations (taxes, insurance, upkeep, occupancy) stated as prominently as benefits.
- HUD-approved counseling explained before the application step.
- No age-based ad targeting on Meta; creative speaks to families instead.
We explain public rules; we don't give legal advice. Your compliance team approves every funnel before launch. Mortgage ad compliance, explained.
What we watch
Numbers that tell us it's working
- 1Family-researcher share
- 2Counseling-explainer views
- 3Calls booked
- 4Time to application
On Funnel Stack and Full Library we test one or two changes a month (a headline, a question order) and report what moved.
Included with this funnel
- Landing page, 4-question quiz and result page, written and built
- Application handoff, pre-filled from the quiz
- 4-touch follow-up in the CRM (SMS with consent, email, tasks)
- 2 ad angles written to avoid unbalanced trigger terms
- Schema, FAQs and your NMLS / Equal Housing block on every page
Not included
- Ad spend (paid to Meta or Google from your account)
- Legal or compliance approval (your compliance team)
- Loan decisions — those stay with you
FAQ
Reverse mortgage (HECM-aware) funnel questions
Specific to the reverse mortgage (hecm-aware) funnel. General questions live on the FAQ page.
Can't find it? Search every answer or ask the funnel desk.
What is a HECM?
A Home Equity Conversion Mortgage is the FHA-insured reverse mortgage for homeowners aged 62 and older. It lets them convert part of their home equity into payments, a lump sum or a line of credit, with no monthly mortgage payment required as long as they meet the loan terms.
Why is the funnel so careful?
Reverse mortgages have a history of misleading ads; the CFPB published research warning about them. Clear, balanced copy protects older homeowners and protects your licence. It also converts better with adult children, who are often the researchers.
Does the funnel explain counseling?
Yes. HECM borrowers must complete counseling with a HUD-approved counselor before applying. The result page and follow-up explain this and link HUD's counselor search so families see it as a normal step.
Why no automatic texts?
Older homeowners and families often prefer a call or email, and an aggressive text sequence feels wrong for this product. SMS only runs if they tick the consent box, and the cadence is slower than other funnels.
Can family members book the call?
Yes. "For my parent(s)" is an answer option and the booking page lets them add a second attendee. The LO's notes show who is researching.
Can we say the money is tax-free?
Avoid blanket tax claims. Proceeds are generally treated as loan advances rather than income, but tax situations vary and borrowers should ask a tax professional. Our copy says that.
What obligations does the page list?
Living in the home as the primary residence, paying property taxes and homeowners insurance, maintaining the property, and the loan becoming due when the last borrower moves out, sells or dies. These sit next to the benefits, not in fine print.
Should every LO run this funnel?
Only LOs who originate reverse mortgages and are comfortable with the product. We leave it out of libraries for LOs who do not.
No question matches that.
Try fewer words, pick "All", or send us the question — we answer within one business day.
Next stage: booked
Launch the reverse mortgage (hecm-aware) funnel in about two weeks
Book a call and we'll review your programs, traffic sources and compliance requirements, then send a written plan for this funnel.
Free 25-minute call · month-to-month plans · no ad spend required to start