 HELOC funnel
A HELOC funnel for homeowners who love their current rate
Many homeowners hold first mortgages with rates they do not want to give up. A home equity line can fund a kitchen or pay off cards without refinancing — if the borrower understands it. This funnel explains, then books.
Included in every plan · or add to any plan for $59/mo
Question 1 of 4
Roughly what is your home worth?
Question 2 of 4
About how much do you still owe?
Question 3 of 4
What is the money for?
What it is
What is a heloc funnel?
A HELOC funnel is a landing page and quiz for homeowners that estimates available equity from home value and balance owed, asks what the money is for, explains how a line of credit works (draw period, variable rate, repayment), and books an equity review call with a loan officer.
Who it's for
Homeowners with meaningful equity and a first mortgage rate they want to keep, planning renovations, education costs, or consolidation of higher-interest debt.
What makes them search
- Renovation quote in hand
- Card balances growing
- Tuition bill
- Emergency fund concerns
The funnel map
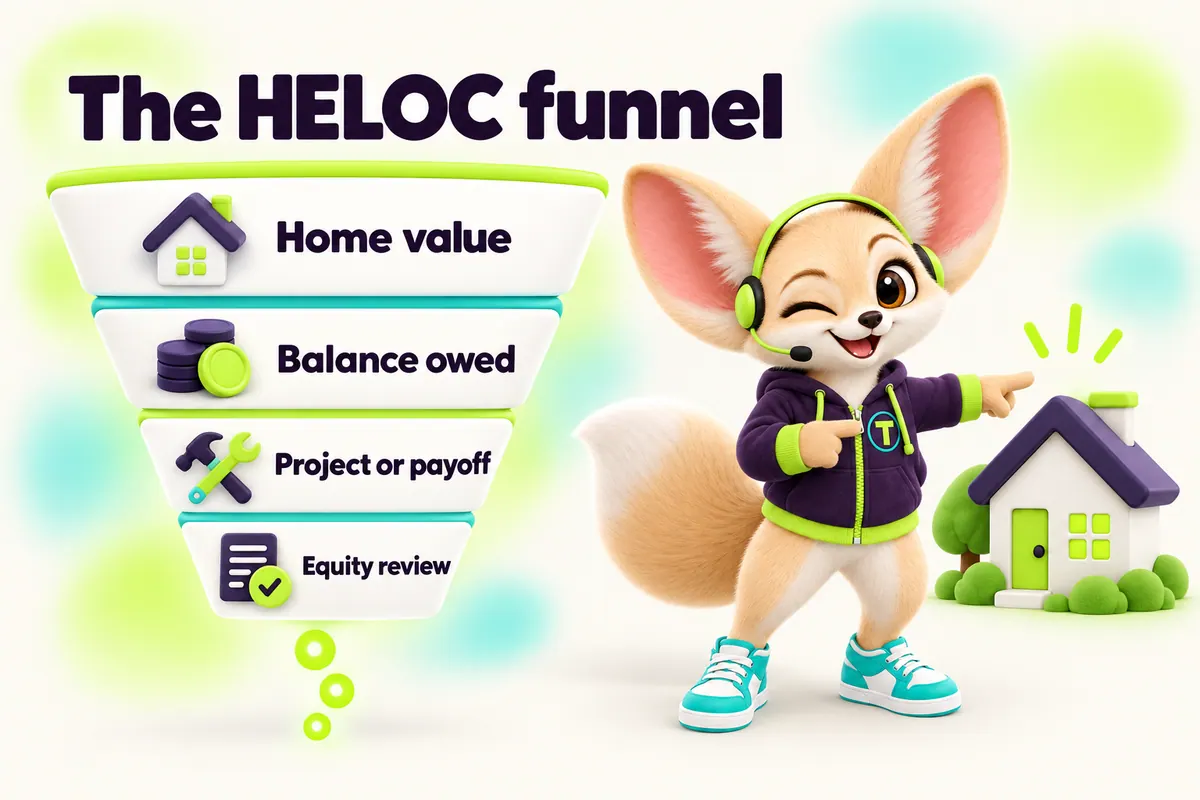
How the HELOC funnel moves a borrower
- 01
Ad or link
Ad angle 1 of 2
Keep your mortgage. Use your equity. See how it works
- 02
Landing page
One screen, one promise
A HELOC funnel is a landing page and quiz for homeowners that estimates available equity from home value and balance owed, asks what the money is for, explains how a line of credit works (draw period, variable rate, repayment), and books an equity review call with a loan officer..
- 03
4-question quiz
Tap-only answers
Roughly what is your home worth? · About how much do you still owe? · What is the money for? · When would you need it?
- 04
Result page
Next step, no promises
The result page shows an illustrative equity range, explains combined loan-to-value in one paragraph, and covers how HELOCs work (draw period, variable rate, repayment period). It offers a call and a link to the cash-out comparison.
- 05
Handoff & follow-up
4 touches written for you
Value band, balance band and purpose sync to the CRM; the LO sees whether to discuss HELOC, home equity loan or cash-out.
The questions, word for word
Four taps. No paperwork yet.
This is the quiz we write for you (your edits welcome). Every answer is a button, so it works one-handed on a phone.
Question 1
Roughly what is your home worth?
- Under $300k
- $300k–$600k
- Over $600k
- Not sure
Question 2
About how much do you still owe?
- Under 50% of value
- 50%–70%
- Over 70%
- Paid off
Question 3
What is the money for?
- Renovation
- Pay off debts
- Education
- Safety cushion
Question 4
When would you need it?
- This month
- 1–3 months
- Just planning
Result page
What the borrower sees next
The result page shows an illustrative equity range, explains combined loan-to-value in one paragraph, and covers how HELOCs work (draw period, variable rate, repayment period). It offers a call and a link to the cash-out comparison.
Follow-up, written for you
What happens after they tap "done"
The follow-up below runs from the CRM included with your site. Texts only go to borrowers who ticked the SMS consent box. Messages are sample copy — we tailor them to your voice.
- 0–30 secondsSMS
Hi {first}, {LO} here — thanks for checking your equity. Want a quick call to look at options for your {purpose}? {calendar} Reply STOP to opt out.
- 15 minutesEmail
"HELOC vs cash-out refinance: which fits?" — a fair comparison.
- Day 2Task
Call task for the LO with value and balance bands.
- Day 7Email
"What a draw period is" — short explainer with a calendar link.
Ads & compliance
Ad angles that work — and stay compliant
Sample ad angle
"Keep your mortgage. Use your equity. See how it works"
Benefit + education; no APR in the ad.
Sample ad angle
"Planning a renovation? Estimate your home equity in 60 seconds"
Project angle with an equity estimate, not an offer.
Compliance built in
- HELOC ads have their own Reg Z trigger rules (12 CFR 1026.16); we keep APRs and payment terms out of ads unless fully disclosed.
- Variable-rate nature explained plainly on the result page.
- No "free money" or "cash in your home" hype.
- Equity estimates labelled as illustrative, not an offer.
We explain public rules; we don't give legal advice. Your compliance team approves every funnel before launch. Mortgage ad compliance, explained.
What we watch
Numbers that tell us it's working
- 1Equity estimate completions
- 2Purpose mix (renovation vs debt)
- 3Booked calls
- 4HELOC vs cash-out split
On Funnel Stack and Full Library we test one or two changes a month (a headline, a question order) and report what moved.
Included with this funnel
- Landing page, 4-question quiz and result page, written and built
- Application handoff, pre-filled from the quiz
- 4-touch follow-up in the CRM (SMS with consent, email, tasks)
- 2 ad angles written to avoid unbalanced trigger terms
- Schema, FAQs and your NMLS / Equal Housing block on every page
Not included
- Ad spend (paid to Meta or Google from your account)
- Legal or compliance approval (your compliance team)
- Loan decisions — those stay with you
FAQ
HELOC funnel questions
Specific to the heloc funnel. General questions live on the FAQ page.
Can't find it? Search every answer or ask the funnel desk.
Why run a separate HELOC funnel instead of a refinance funnel?
Because the borrower's motive is different. Many homeowners want cash without replacing a low first-mortgage rate. A refinance funnel would push them toward the wrong product; a HELOC funnel speaks to their actual situation.
Does the funnel show an APR?
No. HELOC advertising has specific Regulation Z rules (12 CFR 1026.16), and APRs change with the index. The page explains how pricing works in general and the LO quotes on the call.
How is the equity estimate worked out?
From the value and balance bands the borrower picks. The page shows an illustrative range and explains combined loan-to-value. It is labelled as an estimate, not an offer, and the LO confirms with real numbers.
What if my company does not offer HELOCs?
Then we point the result page at a home equity loan or a cash-out refinance instead, or we skip this funnel. We only build funnels for products you actually offer.
Can the funnel compare HELOC and cash-out side by side?
Yes. The follow-up email includes a fair comparison table: rate type, effect on the first mortgage, closing costs, and when each tends to fit. Borrowers often book the call after reading it.
Is a HELOC funnel only for wealthy homeowners?
No. Many middle-income homeowners have built equity over recent years. The quiz uses broad bands so nobody feels judged, and the copy focuses on purpose, not net worth.
What happens if someone owes more than 70% of their home value?
The result page explains that options may be limited and suggests a call to review. We do not tell people they qualify or do not; the LO reviews the actual file.
Can we advertise HELOCs on Meta?
Yes, inside Meta's Special Ad Category for financial products and services, which limits targeting options. Creative and copy do the work instead of narrow targeting.
No question matches that.
Try fewer words, pick "All", or send us the question — we answer within one business day.
Next stage: booked
Launch the heloc funnel in about two weeks
Book a call and we'll review your programs, traffic sources and compliance requirements, then send a written plan for this funnel.
Free 25-minute call · month-to-month plans · no ad spend required to start