Guide · mortgage ad compliance
Mortgage advertising compliance, explained in plain words
Hover or tap the highlighted words in the sample ad. Each one is a trigger term — fine to use, but only with the disclosures it triggers. Our funnels are written to avoid them unless your compliance team approves the full set.
Orientation only, not legal advice. Primary sources: CFPB — Regulation Z §1026.24, Meta — Special Ad Categories. Checked 2026-10-19.
Buy your first home with just !
Lock a loan at with payments from . lender.
Tap a highlighted phrase
Renting and wondering if you could buy? Four quick questions show you the first steps first-time buyers take.
Regulation Z
What are trigger terms in mortgage ads?
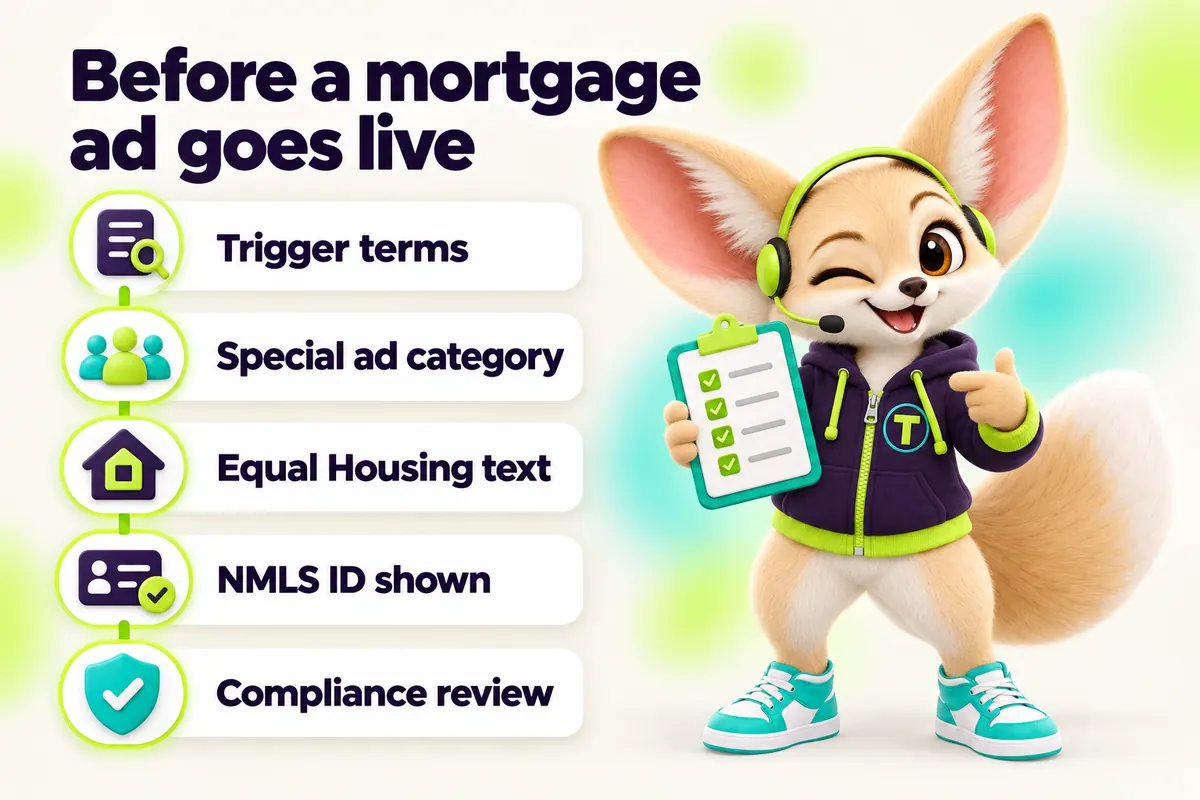
Trigger terms are specific numbers in a credit ad — a down payment, a repayment period, a payment amount or a finance charge — that require extra disclosures under Regulation Z §1026.24(d). If an ad uses one, it must also state the down payment, the repayment terms and the APR, including whether it may increase.
| If the ad states… | Example | …it must also disclose |
|---|---|---|
| Down payment amount or percentage | "Just 3.5% down" | Down payment, terms of repayment and the APR (and whether it may increase). |
| Number of payments or repayment period | "30-year fixed" | Same three disclosures. |
| Amount of any payment | "Payments from $1,450/mo" | Same three disclosures. |
| Amount of any finance charge | "Only $995 in fees" | Same three disclosures. |
| A rate of finance charge | "5.99% rate" | The rate must be stated as an APR (a simple interest rate may appear alongside, not more prominently). |
Summary of 12 CFR 1026.24 for closed-end credit; HELOC ads follow §1026.16. State laws may add requirements. Source: CFPB, checked 2026-10-19.
Ad platforms
Meta and Google targeting limits
Platforms restrict targeting for housing and credit ads to reduce discrimination. Good funnels don't need narrow targeting — the creative and the quiz do the qualifying.
Meta (Facebook, Instagram)
- Mortgage ads run in a Special Ad Category
- No targeting by age, gender or ZIP code
- Location targeting uses a minimum radius
- Detailed targeting options are limited
- Housing and credit ads can't be personalised by gender, age, parental status, marital status or ZIP code (US and Canada)
- Some financial services ads need advertiser verification
- Landing page experience affects ad quality
Before it runs
What every mortgage ad and funnel shows
- NMLS IDs — the loan officer's and the company's, where required.
- Licence lines — state licensing statements your company specifies.
- Equal Housing Opportunity — statement as text, official logo if you supply it.
- No implied government affiliation — no seals, no "VA approved".
- Balanced claims — no "guaranteed approval", no "lowest rate".
- Privacy and consent — privacy link and SMS consent next to every form.
How we work with your compliance team
Written carefully, approved by you
- 01
We write conservatively
Ads and pages are written without trigger terms by default; benefits are described in words, not numbers.
- 02
We flag what needs review
Every draft ships with a compliance summary: claims made, programs named, any numbers and their source.
- 03
Your compliance team approves
Nothing launches without written approval from you, and from your compliance contact where your company requires it.
- 04
We keep a record
Approved versions and dates are stored, so you can show what ran and when.
FAQ
Mortgage ad compliance questions
Plain-English orientation with sources. Your compliance team has the final word.
Can't find it? Search every answer or ask the funnel desk.
What are trigger terms in mortgage advertising?
Trigger terms are specific credit terms that, under Regulation Z (12 CFR 1026.24(d)), require additional disclosures if they appear in an ad for closed-end credit: the amount or percentage of a down payment, the number of payments or period of repayment, the amount of any payment, and the amount of any finance charge. If one appears, the ad must also state the down payment, the terms of repayment and the APR, including whether it may increase.
Is "low down payment" a trigger term?
General phrases without numbers — "low down payment", "flexible terms" — are generally not trigger terms under Regulation Z, while "3.5% down" is. Your compliance team makes the final call, especially for state rules that go further.
What is Meta's Special Ad Category for mortgage ads?
Meta requires ads about housing and financial products and services, including mortgages, to run in a Special Ad Category. These ads cannot target by age, gender or ZIP code, location targeting has a minimum radius, and detailed targeting options are limited — to reduce discriminatory targeting.
Does Google restrict mortgage ad targeting?
Yes. Google's personalized advertising policy restricts housing and credit ads in the US and Canada from targeting by gender, age, parental status, marital status or ZIP code. Some financial services ads may also require advertiser verification.
Do I need my NMLS ID in ads?
Most states require a mortgage loan originator's NMLS unique identifier in advertising, and many companies require it everywhere. We put your NMLS ID — and your company's — on every funnel page and in ad copy where space allows; your compliance team confirms the format.
Do funnel pages need the Equal Housing Opportunity logo?
Requirements depend on the lender's regulator and type, and many companies require it on all marketing. We show the Equal Housing Opportunity statement as text on every page, and the official logo where your company provides it.
Can I say "VA approved" or use government seals?
No. Regulation N (the Mortgage Acts and Practices — Advertising rule) prohibits misrepresenting an affiliation with a government agency. We never use government seals or imply the LO is the VA, FHA or HUD.
Can real estate agents pay for part of my ads?
RESPA Section 8 prohibits giving or accepting anything of value for referrals of settlement service business. Co-marketing is possible when each party pays its fair share at fair market value — get compliance approval and document it.
Do you provide legal advice?
No. This page summarises public rules for orientation, with links to primary sources. We are a website and marketing provider, not a law firm; your company's compliance team or counsel approves your advertising.
Are texts and calls covered by advertising rules too?
Texts and calls are covered by the TCPA and related rules on consent, and the content of a text is still advertising. Our follow-up messages avoid trigger terms and include opt-out language.
No question matches that.
Try fewer words, pick "All", or send us the question — we answer within one business day.
Next stage: booked
Funnels your compliance team can approve quickly
Every draft comes with a compliance summary. Book a call and we'll show you one.
Free 25-minute call · month-to-month plans · no ad spend required to start